Step Wise Guide to Improve Your Credit Score for Home Loan in 2026
Overwhelmed to find an apartment that meets your expectations! Now, comes the time to walk into the bank. Interestingly, there is only one barrier between you and a home loan: your credit score for home loan approval. As a homebuyer in 2026, you must know that a single red flag on your credit report is sometimes all it takes for a lender to say no. Unfortunately, most first-time buyers discover it after they've already applied. This Star Estate blog takes you through what your credit score actually means and how to check it. Importantly, it also explains how to improve your credit score before you apply for a home loan in India in 2026.
Most banks and other housing finance companies consider a CIBIL Score of at least 700. However, applicants with 750 or more are considered to be eligible for a better home loan interest rate. Below 650, approval gets tougher, and you'll likely receive a higher interest rate and a lower sanctioned amount. Some with a poor or low credit score need a co-applicant with a stronger score.
What Is a Credit Score?
A credit score is a three-digit number, typically between 300 and 900. The score reflects your loan affordability depending on your past repayment patterns. Banks and other financial housing finance companies use credit scores to assess risk, in the shortest possible time and a standardised way, before they sanction lakhs of rupees. Even crores in some cases.
In India, a credit score is also called the CIBIL score. Named after TransUnion CIBIL, the country's oldest and most widely used credit bureau. The RBI (Reserve Bank of India) has authorised four credit bureaus in total — TransUnion CIBIL, Equifax, Experian, and CRIF High Mark. CIBIL is the first number to be checked when it comes to a home loan application. The credit score is calculated based on your past credit history. Including every EMI, every credit card bill, every loan you've ever taken, and your existing loans.
Steps to Check Your CIBIL Score
Every individual is entitled to free CIBIL report every calendar year. You can check the same on a regular basis at no cost. The credit score can be checked on multiple platforms, as per your convenience.
1. Via the Official CIBIL Website
Visit cibil and choose the free annual credit report option.
Enter your PAN, date of birth, and a few identity details.
Verify via OTP and download your score and full report.
2. Via Your Bank App/ Any Banking or financial lending App
Most net-banking and financial lender apps now show a live CIBIL score for free
3. When Apply for the Home Loan Application
Your lender will run its own CIBIL Score check once you formally apply
CIBIL Score for Home Loan in India in 2026
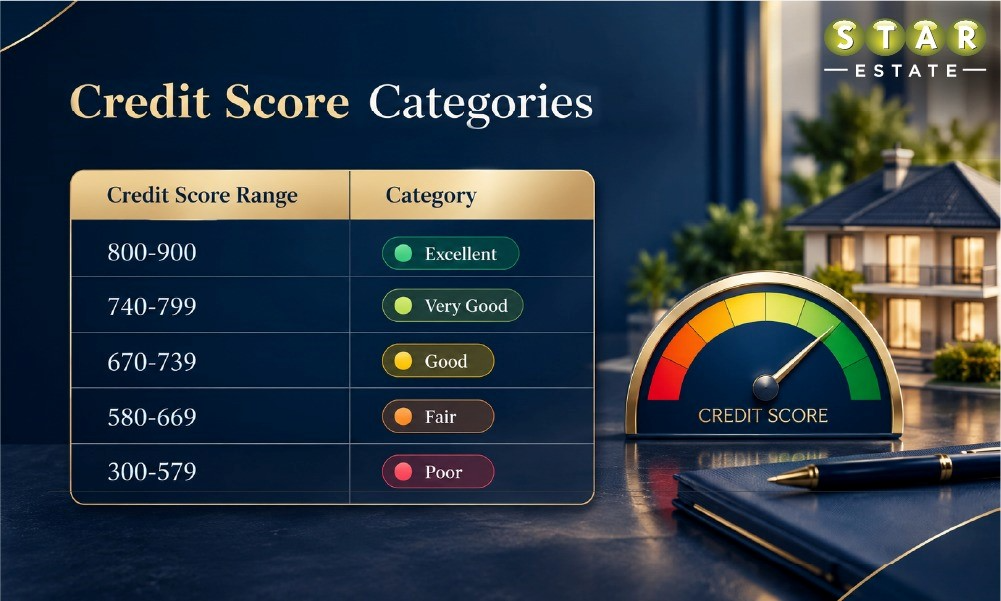
The credit score for a home loan has a standard range to assess your loan repayment affordability. However, the final decision to disapprove or move forward with the loan application depends on the discussion between you and the loan lender.
A credit score for home loan approval of 750 or above positioned you in the excellent category. It is the best pricing bracket for lenders to go ahead with your loan application.
A credit score between 700 and 749 ranks you in the Good category. Hence, your home loan application is likely to be approved, but with slightly higher rate of interest.
However, anything between 650 and 699 is considered fair, and there is a good possibility that banks will ask you to add a co-applicant to the loan application. It enhances the loan repayment, and the attached applicant acts as your guarantor for the loan.
A score between 600 and 649 is marked as poor, and the possibility of a home loan sanction tightens with add-on provisions. Such as the addition of a co-applicant or a higher down payment. The attachment of both works better for the home loan applicant.
A score below 600 is actually poor and holds maximum chance of home loan rejection.
For instance, SBI (State Bank of India) has a credit-score-linked pricing model. Based on this, the home loan interest rates commence from approximately 6.70% for its highest-scoring borrowers, While, ICICI Bank's general home loan slab offer from roughly 7.3% to 9.5% depending on your profile.
That difference between the top and bottom of the range can add up to lakhs of rupees in extra interest over a loan tenure of more than 20 years. Thus, it’s important to improve your CIBIL score before applying for a home loan in 2026.
Factors That Affect Your Credit Score for Home Loan in 2026
A CIBIL score is one metric built from multiple factors as key components. Here, Star Estate lists all the determinants you must check when analysing your credit score.
Repayment History
It has major weight. Even a single bounced EMI or an unpaid credit card bill is marked as a red flag. Interestingly, even a few days' pending time before the bill clears is taken into consideration. It is enough to pull down your credit score for a home loan in 2026. Therefore, we suggest that you pay bills and EMIs on time to avoid unclear dues issues.
Credit Utilisation Ratio
This measures your actual credit usage out of the credit limit given by the bank. Don't assume that paying your bill in full each month works in your favour. Rather, spending anywhere close to your credit limit is a red flag for lenders. In simpler terms, it's the habit of mixing out that hurts your score — not just carrying unpaid debt.
Length and Mix of Credit
A longer-duration credit history with mixed secured loans reflects you as a loan borrower who can handle multiple EMI obligations. The secured loans can include a car loan and an existing home loan. Also, some lenders may consider unsecured loans, including credit cards and personal loans. However, a balance in both can work in your favor when applying for a home loan in 2026.
Why Does a Healthy Credit Score for Home Loan Matter in 2026?
Along with demand for residential properties, home loan requirements are also climbing through 2026. After the Reserve Bank of India’s Monetary Policy Committee held the repo rate steady at 5.25% through the middle of the year, homebuyers have become more confident. The decision has kept lending rates relatively stable, thus attracting first-time buyers. Mainly in Tier 2 and Tier 3 Indian cities.
With a higher number of loan applications in the queue, the banks and other financial lenders become more vigilant. The home loan eligibility criteria become more stringent, while the focus remains on affordability. A strong credit score for home loan applications speeds up the loan approval process. It saves loss of time, as banks don’t go back-and-forth looking for a middle way out. A low or poor credit score for a home loan in 2026 may require a co-applicant or settlement of unpaid dues.
That said, even when these factors work in your favour, it takes time for the improvement to reflect in your credit score. Delay too long, you risk losing out — not just on time, but on the property that best fits your budget.
Ways to Improve Your Credit Score for Home Loan in India
Improving your credit score for home loan approval can’t be done overnight. But regular effort and routine can help you attain the desired credit score for a home loan in 2026.
Things to fix in 30–60 Days
Clear any overdue credit card or EMI dues immediately, even small ones
Check your CIBIL report and dispute any factual errors — check for wrongly marked ‘late payment’ and connect with your banking representative to fix the same.
Bring your credit utilisation below 30% of your total limit on every card.
Maintain Discipline in 3–6 Months
Pay every EMI and credit card bill on or before the due date, without exception
Avoid applying for new credit cards or personal loans while you're preparing to apply for home loan
Keep old credit cards open rather than closing them, even if you rarely use them
Just Before Applying for Home Loan in 2026
Consider a joint home loan with a spouse or parent who has a stronger score
Offer a higher down payment to lower your loan-to-value ratio, which reduces lender risk
Avoid standing as a guarantor for anyone else's loan in the run-up to your own application
If you're weighing your options against how much loan you can realistically service, try Star Estate’s EMI calculator you map that out before you start talking to lenders.
What's Next for Credit Score and Home Loan Trends in India
In the coming months, banks and financial lenders may incline further toward credit-score-linked pricing. Following SBI's lead means the gap in interest rates between a good and an excellent score is likely to widen.
While the repo rate is stable, home loan affordability is likely to stay stable by the end of 2026. But loan sanction is likely to be successful for those with a healthy credit score. Those with a poor or average credit score for a home loan may witness disappointment. Therefore, you must fix your CIBIL report at least a few weeks or months before applying for a home loan in 2026.
Your Credit Score Is Just the First Step to Your Home Buying Journey
A good credit score gets your loan file moving at a fast pace. But it doesn't find you the right residential property, nor does it help you negotiate the price. That's where Star Estate's expertise makes the difference. From market condition knowledge to collaborating with RERA-verified developers. We strategize property search for you based on your requirements. Connect with a Star Estate advisor today for a free consultation on RERA-verified projects that fit your budget, after checking your credit score for a home loan in 2026